Claim denied or underpaid? A homeowners insurance claim lawyer who reads the fine print.
A homeowners insurance claim lawyer makes your insurer honor the policy you paid for. In Orlando and across Florida, we fight denied, delayed and underpaid claims for water, fire, wind and roof damage. We read the policy, document the damage with independent experts and push for the full payment. No fee unless we recover.
Your home stays damaged while the insurer decides
We’re sorry this happened to your home. Every day with water in the walls or a hole in the roof makes it worse. And Florida insurers know many families take the first number they’re offered.
The denial letter
“Wear and tear,” “pre-existing damage,” “not covered.” Many denials don’t survive a careful read of the policy.
The lowball estimate
The insurer’s adjuster prices the repair far below what real contractors charge.
Delays and more paperwork
Request after request for documents, or an examination under oath, while your home waits.
What waiting can cost you
The one-year notice
A new claim must be reported within one year of the date of loss.
Damage spreads
Today’s leak is next month’s mold. Your policy requires you to prevent further damage.
What you sign
Cashing a check or signing certain forms can limit what you can claim later.
Your deductible
A low payment can leave you with almost nothing once the deductible comes off.
The insurance company has a team. Now you do too.
Get my free case reviewFlorida law, in plain words
The rules for homeowners claims in Florida
Florida rewrote its property insurance laws several times between 2021 and 2023. Some deadlines got shorter, but insurers have firm duties too. Here’s what matters most.
Your notice deadlines
A new or reopened claim must be reported within one year of the date of loss. A supplemental claim, for extra damage or a higher repair cost, has 18 months.
The insurer’s deadlines
Your insurer must acknowledge your claim within 7 days and pay or deny it within 60 days of notice, unless something outside its control prevents it.
A written explanation
If the insurer denies all or part of the claim, or pays less than its own estimate, it must explain why in writing, tied to the policy language.
Your duties after a loss
Protect the home from further damage, keep receipts, allow an inspection and provide the documents the policy requires.
Ways to resolve a dispute
Florida’s state mediation program, the appraisal clause in many policies and, after written notice to the insurer, a lawsuit for breach of the policy.
To report a new claim
1 year
That’s the deadline to give your insurer notice from the date of loss. If your claim has been denied or underpaid, don’t wait to get it reviewed.
What we see in Central Florida
The homeowners claims insurers fight most
Storms get the headlines, but most homeowners claims start on a normal day: a burst pipe, a kitchen fire, a slow leak that finally shows through the ceiling. We bring in independent adjusters, engineers and contractors so the insurer isn’t the only one with an expert.
Burst pipes and water damage
Sudden leaks that ruin floors, cabinets and drywall, and the mold that follows. Insurers often call them “long-term leaks” to deny them.
Fire and smoke
The structure, smoke damage throughout the home, your belongings and the cost of living elsewhere during repairs.
Roof leaks
Insurers blame age and wear. An independent inspection can show the damage came from wind or hail.
Citizens and private insurers
Citizens Property Insurance and private carriers have different procedures, but both must pay what the policy covers.
What your policy may cover
Every policy is different, so we start by reading yours. These are the coverages insurers most often underpay.
- Repairing or rebuilding your home at real contractor prices
- Damaged belongings: furniture, appliances, clothing and electronics
- Additional living expenses if you can’t stay in your home
- Emergency repairs to stop further damage, like tarps and water extraction
- Debris removal and, where the policy covers it, mold remediation
- Code upgrades required by the building department, if you have ordinance or law coverage
Proof, not promises
Real people, real results
Recovered on a homeowners claim
[$X]
[Damage type, city and year: one sentence on the first offer and the final recovery.]
Every case is different. Past results don’t guarantee a similar outcome.
“Our insurer paid us almost nothing for a burst pipe that ruined the whole kitchen. Sunshine got an independent estimate and kept pushing until they paid the full repair.”
Placeholder result and sample review shown for layout. Replace with a verified result and a real Google review, approved under Florida Bar Rule 4-7, before launch.
Three simple steps
Your homeowners claim, in three steps
- 1
Send us the letter
A free call with an attorney, in English or Spanish. Send your policy and the insurer’s letter, and we’ll tell you where you stand.
- 2
We document the damage
We review the policy, bring in independent experts and build a claim the insurer can’t brush aside.
- 3
We push for full payment
We negotiate hard, use mediation or appraisal when it helps and, if the insurer won’t be fair, file suit.
Where you end up: home, repaired
Before
- A denial letter and a damaged home
- Alone against the insurer’s adjuster
- Paying for repairs out of pocket
With Sunshine
- A clear read of what your policy covers
- Independent experts on your side
- Your home repaired
Your home repaired
A payment that covers what the repair really costs.
Your policy honored
The insurer delivers what you paid for all those years.
Your costs covered
Emergency repairs and temporary housing included.
Peace of mind
No more endless calls and paperwork. We handle it.
Every case is different. Past results don’t guarantee a similar outcome.
Our promise
We treat your case as if it were our own.
What it costs, and why Sunshine
Homeowners insurance attorneys who read every page
After damage to their home, most Florida homeowners end up arguing with an insurer that has adjusters, engineers and lawyers. Sunshine State Law Firm takes on that fight and keeps you informed every step of the way, so you can get your home back. No fee unless we recover for you.
- No fee unless we recover for you. The percentage is in writing before you sign, along with the Statement of Client’s Rights Florida requires.
- You’ll always know who’s handling your case, with updates by text, email and phone.
- Hablamos español, from the first call to the final check.
- No question is a dumb question. We explain every step in plain words.
Guides for Florida homeowners
When you need a homeowners insurance attorney in Florida
When a Florida homeowners insurance attorney can help with a denied or underpaid claim, what they do at each stage, and how 2022 law changes affect you.
Read the guide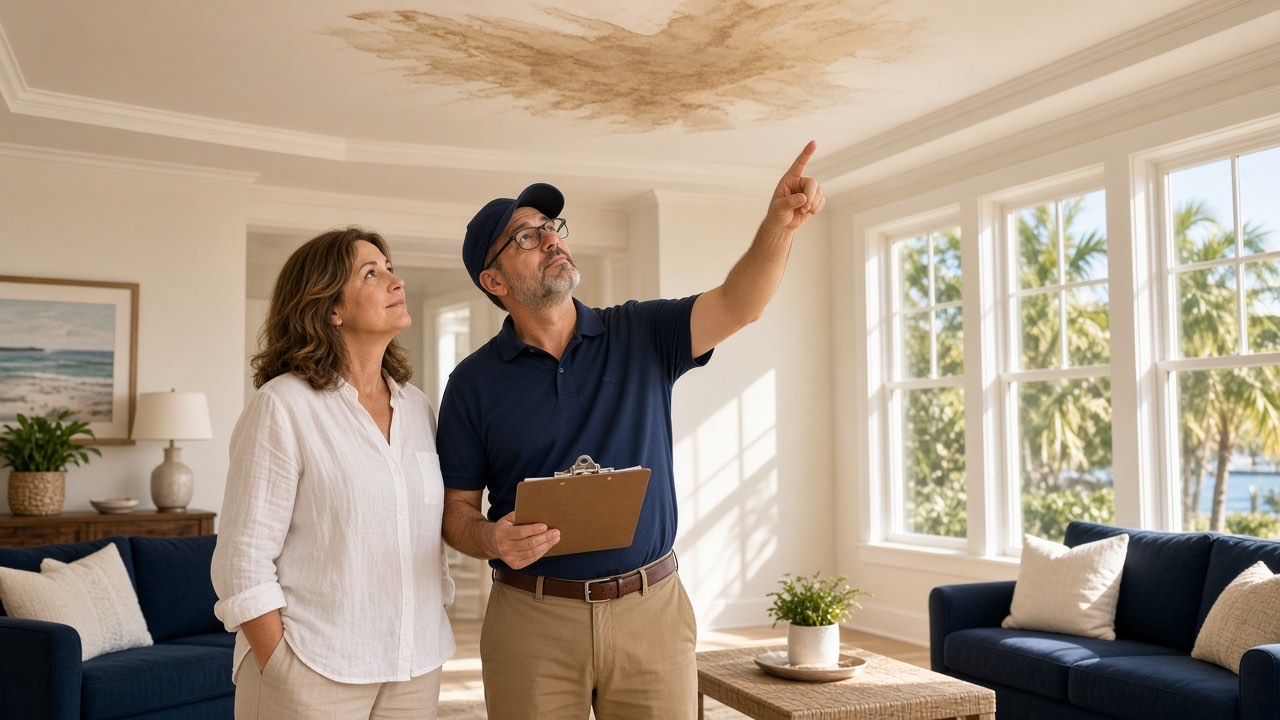
Do I need an insurance lawyer? 5 ways to know
Do I need an insurance lawyer? Five signs your Florida home insurance claim needs legal help, plus when you can safely handle it on your own.
Read the guide
Florida Senate Bill 76: what homeowners need to know
Florida Senate Bill 76 changed how homeowners insurance claims and disputes work. What it did, what the 2022 reforms added and what it means for you today.
Read the guide
Homeowners claim questions we hear every day
No question is a dumb question. Here are the ones we hear most.
Get the denial in writing, keep the letter and your full policy, and photograph the damage. Many denials can be challenged. A homeowners insurance claim lawyer can review the letter and policy for free and tell you whether it’s worth fighting.
Do I need an insurance lawyer? 5 ways to knowYou must give your insurer notice of a new or reopened claim within one year of the date of loss, and of a supplemental claim within 18 months. The deadline to sue the insurer is separate, so get advice early.
Nothing up front. We work on a contingency fee: our fee is a percentage of what we recover, and you owe no attorney’s fee if we don’t recover. The percentage and how case costs are handled are in a written agreement you see before you sign.
Often, yes. If you find more damage or the real repair cost is higher, you may be able to file a supplemental claim within 18 months of the loss. Have an attorney review anything you signed.
Citizens Property Insurance has its own procedures, but it still has to pay what your policy covers. We handle claims against Citizens and private insurers alike.
Make the emergency repairs needed to stop further damage, like a tarp or water extraction, and keep every receipt. Photograph and video everything before you change it, and wait for the inspection before permanent repairs.
Tell us your story. We’ll take it from here.
A free, personal conversation with an attorney. No pressure, no fee unless we recover for you.
Hablamos español · Consulta gratis