Hurt in a crash? Let an Orlando car accident lawyer handle the insurance company.
An Orlando car accident lawyer deals with every insurer after a Florida crash, from your own PIP carrier to the at-fault driver’s company, while you heal. We gather the evidence, track your treatment and push for a fair settlement, or go to trial. The case review is free, and there’s no fee unless we recover.
The days after a crash decide more than you think
We’re sorry this happened. A crash turns an ordinary drive into weeks of appointments, repair estimates and phone calls, often while you’re in pain. Meanwhile, the insurance companies are already working the claim.
The quick lowball offer
A fast check, before you know whether you’ll need an MRI, injections or surgery.
The recorded statement
The other driver’s adjuster calls to “get your side.” Your words can be used to argue fault or downplay your injuries.
The fault fight
The insurer suggests you were speeding, distracted or stopped short, because every point of blame lowers what they pay.
What waiting can cost you
The 14-day window
Miss it, and your PIP may not cover your treatment at all.
The two-year deadline
Most Florida crash claims must be filed within two years, or the claim can be lost.
Over 50% at fault
If the insurer makes that stick, Florida law bars your recovery.
PIP runs out fast
$10,000 covers a few visits and scans. Surgery and therapy can cost far more.
The insurance company has a team. Now you do too.
Get my free case reviewFlorida law, in plain words
Who pays after a Florida car crash
Florida is a no-fault state, which means your own insurance pays first, no matter who caused the crash. But no-fault only goes so far. A serious crash usually involves several policies, and each insurer looks out for itself.
| Coverage | Whose policy | What it pays |
|---|---|---|
| Personal injury protection (PIP)Yours, or a household member’s | Yours, or a household member’s | 80% of reasonable medical bills and 60% of lost income, up to $10,000, no matter who caused the crash. Treatment must start within 14 days. |
| Property damage liabilityThe at-fault driver’s | The at-fault driver’s | Repairing or replacing your car, up to their limit. Florida requires at least $10,000. |
| Bodily injury liabilityThe at-fault driver’s, if they carry it | The at-fault driver’s, if they carry it | Medical bills beyond PIP, lost wages, and pain and suffering when your injury meets Florida’s threshold. |
| Uninsured / underinsured motoristYours, unless you rejected it in writing | Yours, unless you rejected it in writing | Steps in when the at-fault driver has no bodily injury coverage, or not enough. |
| Medical payments (MedPay) and collisionYours, if you bought them | Yours, if you bought them | MedPay can cover the 20% of medical bills PIP doesn’t. Collision fixes your car now, minus the deductible. |
When you can claim pain and suffering
Florida’s no-fault law limits claims for pain and suffering against the at-fault driver. To step outside it, your injury has to meet one of these thresholds, and your doctors’ records are what prove it:
- A significant and permanent loss of an important bodily function
- A permanent injury, within a reasonable degree of medical probability
- Significant and permanent scarring or disfigurement
- A death
Fault, since 2023
51%
Florida now uses modified comparative negligence. Your recovery drops by your share of the fault, and if you’re found 51% or more at fault, it’s gone.
Central Florida roads
Orlando crashes have their own patterns
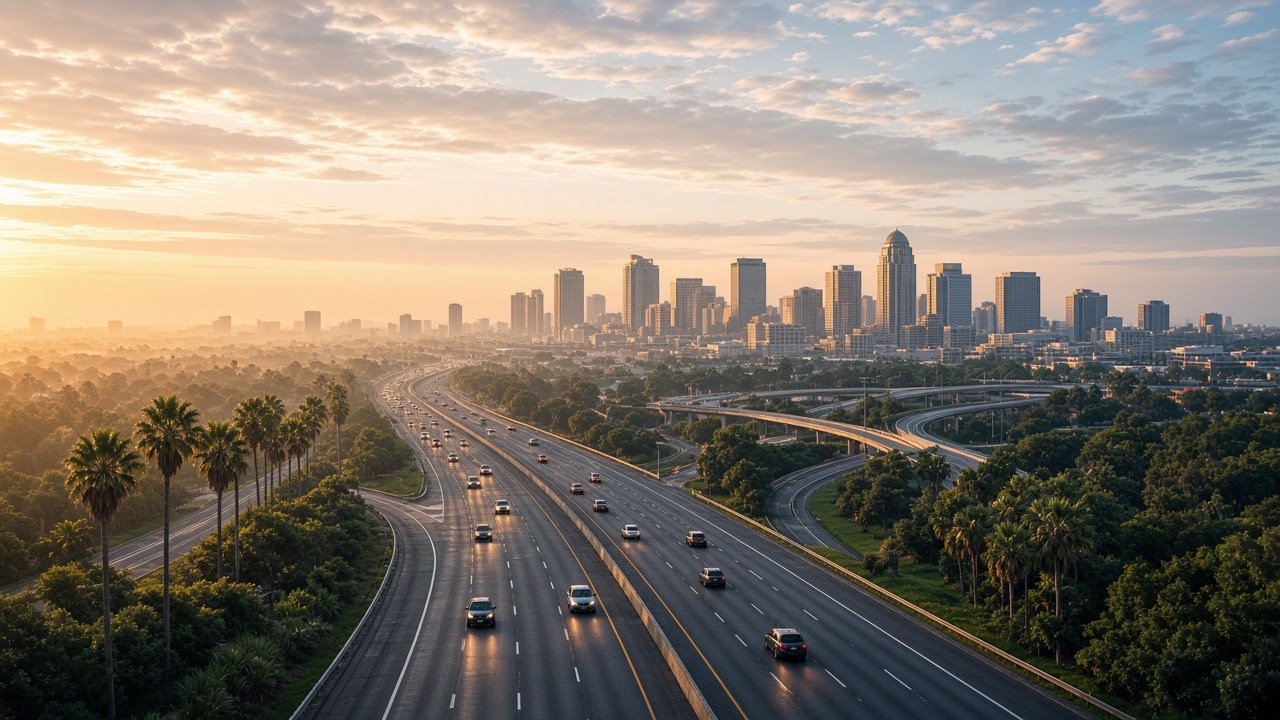
Orange, Seminole, Osceola and Lake counties mix commuters, heavy trucks and millions of visitors. That shapes which insurance applies and what evidence we go after first: dashcam and traffic camera video, the crash report and witnesses.
I-4 and the toll roads
I-4’s stop-and-go stretches mean rear-end crashes. The 408, 417 and the Turnpike move faster, so crashes there tend to be more serious.
Tourists and rental cars
Near the parks, the other driver may be a visitor in a rental. Coverage can come from a policy back home or the rental company, and we sort out which pays.
Rollovers
Rollovers often cause head, neck and spine injuries. When a roof crushed or a seatbelt failed, a claim against the manufacturer may be part of the case.
Drivers with little or no insurance
Florida doesn’t require most drivers to carry bodily injury coverage. When the at-fault driver has none, your uninsured motorist coverage often makes a fair recovery possible.
Hurt as an Uber or Lyft passenger? Read who pays after a rideshare crash in Florida, or see all the injury cases we handle in Orlando.
What you can recover after a crash
PIP is only the start. When another driver is at fault, a claim against their insurance, or your own uninsured motorist coverage, can cover what PIP never will. We don’t send a demand until your doctors can tell us what your recovery will really cost.
- Medical bills PIP didn’t cover, now and in the future
- Lost wages, and lost earning power if you can’t do the same work
- Pain, suffering and the life you couldn’t live while healing
- Your car repaired or replaced, plus a rental while you wait
- Scarring, disfigurement and permanent limits on what you can do
- For families after a fatal crash: funeral costs, lost support and lost companionship
Free checklist
After a Florida crash: the first 14 days
Not ready to call? That’s okay. This checklist covers what to do now so you don’t lose benefits you’re owed.
- The doctor visit that protects your PIP benefits (the 14-day window)
- The photos and records to collect right away
- What not to say to the other driver’s insurer
No sign-up. Check it off on your phone, or print it for your glovebox.
Proof, not promises
Real people, real results
Recovered after an Orlando car crash
[$X]
[Crash type, road and year: one sentence on the injuries and what the recovery covered.]
Every case is different. Past results don’t guarantee a similar outcome.
“I didn’t know how any of this works. Stephanie texted me every step of the way and I never once felt rushed. They treated me like family.”
Placeholder result and sample review shown for layout. Replace with a verified result and a real Google review, approved under Florida Bar Rule 4-7, before launch.
Three simple steps
Your car accident case, in three steps
- 1
Tell us what happened
A free call with an attorney, in English or Spanish. We’ll explain your PIP, your deadlines and what your claim may involve.
- 2
We take over the insurance companies
We notify every insurer, get the crash report and records, and handle the calls, so no one pressures you for a recorded statement.
- 3
You heal, we push for a fair recovery
When your treatment is clear, we send a demand and negotiate hard. If the insurer won’t be fair, we’re ready for trial.
Where you end up: back behind the wheel
Before
- Overwhelmed and in pain
- Alone against the insurance company
- Treated like a claim number
With Sunshine
- Informed at every step
- Protected by a team that fights for you
- Back on your feet
The right doctors
Treatment that actually helps you heal, with second opinions when they matter.
Bills and lost wages recovered
Medical bills covered and the paychecks you missed made up.
Your car repaired or replaced
A fair value for your vehicle, and a rental while you wait.
Peace of mind
No more calls from adjusters. You always know what’s next.
Every case is different. Past results don’t guarantee a similar outcome.
Our promise
We treat your case as if it were our own.
What it costs, and why Sunshine
Car accident attorneys who keep you in the loop
After a crash, most Floridians end up fighting the insurance company alone. Sunshine State Law Firm takes on that fight and keeps you informed every step of the way, so you can heal and get back on the road. No fee unless we recover for you.
- No fee unless we recover for you. The percentage is in writing before you sign, along with the Statement of Client’s Rights Florida requires.
- You’ll always know who’s handling your case, with updates by text, email and phone.
- Hablamos español, from the first call to the final check.
- No question is a dumb question. We explain every step in plain words.
Car accident guides
Should I accept the first car accident settlement offer?
Got a first settlement offer after a car accident? Why early offers run low in Florida, what signing a release means, and how to respond.
Read the guide
What is personal injury protection? Florida PIP explained
What is personal injury protection? How Florida’s no-fault PIP works after a crash, what it pays, the 14-day rule, and when you can sue the other driver.
Read the guide
Car accident mistakes that can hurt your Florida claim
The car accident mistakes that most often hurt Florida injury claims, from skipping the doctor to recorded statements, and what to do instead.
Read the guide
Car accident questions we hear every day
No question is a dumb question. Here are the ones we hear most.
If no one was hurt, often not. If you’re injured, missing work, facing more treatment than PIP covers, or the insurer is blaming you, it usually is. The first conversation is free either way.
Is it worth getting a lawyer for a minor accident?Nothing up front. We work on a contingency fee: our fee is a percentage of what we recover, and you owe no attorney’s fee if we don’t recover. The percentage and how case costs are handled are in a written agreement you see before you sign.
Your own PIP pays first, covering 80% of reasonable medical bills up to $10,000, as long as you get treatment within 14 days. After that, health insurance, MedPay, the at-fault driver’s bodily injury coverage and your uninsured motorist coverage can each play a part.
How medical bills are paid after a crashFor crashes since March 24, 2023, Florida generally gives you two years from the date of the crash to file a lawsuit. The 14-day window to start treatment for PIP comes much sooner, and claims involving a government vehicle have their own notice rules.
Florida injury deadlines, explainedYes, as long as you’re not found more than 50% at fault. Your recovery is reduced by your share of the fault. Your own PIP still pays regardless of fault.
Can I collect if I was at fault?Usually not before you know the full cost of your injuries. Once you accept, you typically sign a release that ends the claim, even if you later need surgery. Have an attorney review the offer first.
Should you accept the first settlement offer?It depends on your medical bills, lost income, whether the injury is permanent, how fault is split and how much insurance is available. No honest lawyer can give you a number on the first call, but we can tell you what will drive it.
How much to expect from a settlementTell us your story. We’ll take it from here.
A free, personal conversation with an attorney. No pressure, no fee unless we recover for you.
Hablamos español · Consulta gratis