When you need a homeowners insurance attorney in Florida
When a Florida homeowners insurance attorney can help with a denied or underpaid claim, what they do at each stage, and how 2022 law changes affect you.
 By Simon NicholsonFounding attorney, Sunshine State Law Firm
Claim denied or underpaid? Talk to an attorney for free. No fee unless we recover.
A homeowners insurance attorney in Florida helps when your insurer denies, underpays or stalls a claim for roof, water, hurricane or fire damage. The attorney reads your policy, documents the loss, handles requests like a recorded statement or proof of loss, and can use appraisal, state mediation or a lawsuit to push for what your policy owes.
You pay premiums every year so that when something goes wrong with your home, you're not facing the repair bill alone. Many claims are paid fairly. But when one isn't, the insurer has adjusters, engineers and lawyers working the file. This guide explains where a homeowners insurance attorney fits in and what changes in Florida law mean for your claim.
What a homeowners insurance attorney does
A homeowners insurance attorney represents the policyholder, not the insurance company. The work usually falls into four parts.
- Reading the policy. Your policy is a contract written by the insurer. It has coverage sections, exclusions, endorsements and conditions you have to meet. An attorney reads all of it and compares it to the reason your claim was denied or reduced.
- Building the record. Many claims are underpaid because the damage wasn't fully documented. An attorney can bring in independent contractors, engineers or other consultants to show the cause of the damage and the true cost of repairs.
- Managing the insurer's requests. Insurers can ask for a recorded statement, a sworn proof of loss (a signed statement of what you're claiming) or an examination under oath (formal sworn questioning). These are policy conditions with real consequences, and it helps to have someone prepare you.
- Resolving the dispute. That can mean negotiating, invoking appraisal, using state mediation, sending the required pre-suit notice and, when needed, filing a lawsuit.
Situations where a homeowners insurance attorney can help
| Situation | What it often looks like |
|---|---|
| Denied claim | A letter citing "wear and tear," "long-term leakage," an exclusion or late notice |
| Underpaid claim | An estimate that won't cover a licensed contractor's price, or that repairs only part of a damaged roof or floor |
| Delayed claim | Weeks without an adjuster visit, repeated document requests, or no decision after two months |
| Lowball check marked "final" | A payment that comes with a release or language closing the claim |
| Disputed cause of loss | The insurer's engineer blames age, construction defects or a non-covered event |
| Large or complex loss | Hurricane, fire or major water damage that involves the dwelling, belongings and living expenses |
Roof claims
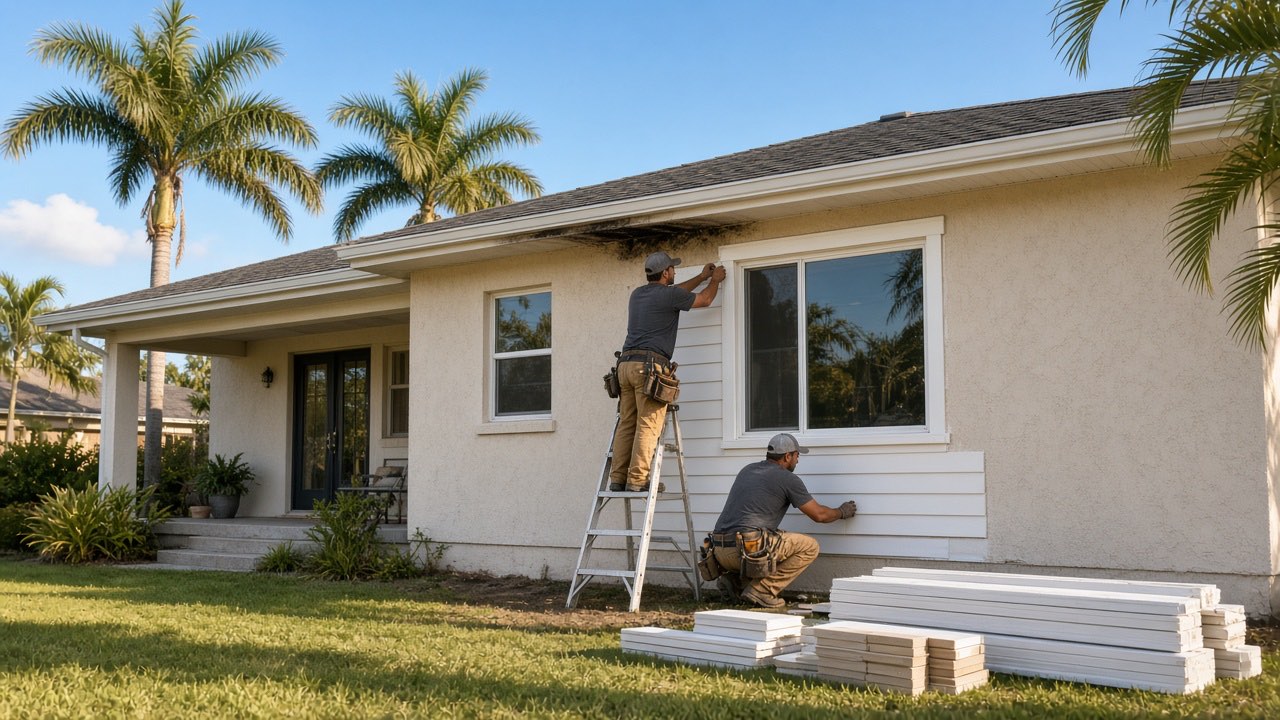
Roof claims are some of the most common homeowners claims in Florida, and some of the most disputed. Insurers often point to age and deterioration, poor installation or a "non-covered occurrence." Your roof can be older and still have real storm damage. We cover this in detail in what to do when your roof insurance claim is denied.
Water and plumbing claims
A sudden pipe burst is usually treated differently from a slow leak. Many Florida policies limit or exclude water damage that happens repeatedly over 14 days or more, and some cap water claims unless you use the insurer's preferred contractor. The exact wording matters.
Hurricane and fire claims
Hurricane claims often involve a separate hurricane deductible, usually a percentage of your dwelling coverage. Fire claims involve smoke, water from firefighting and months of living elsewhere. Our post on what a fire insurance claim lawyer does walks through those coverages.
What Florida law says about your claim
Florida rewrote much of its property insurance law between 2021 and 2022. A few rules matter for almost every homeowner:
- Insurer deadlines. Insurers generally must acknowledge your claim within 7 days and pay or deny it within 60 days of notice, unless factors beyond their control apply (§627.70131).
- Your deadlines. A new or reopened claim generally must be reported within 1 year of the date of loss, and a supplemental claim within 18 months (§627.70132).
- Pre-suit notice. Before filing a lawsuit, you must send a notice of intent to initiate litigation at least 10 business days in advance (§627.70152).
- Homeowner Claims Bill of Rights. Florida requires insurers to give residential policyholders a summary of their rights after a claim, including the right to free mediation through the Department of Financial Services.
- Attorney's fees. Florida ended one-way attorney's fees for property insurance policies issued after the late-2022 reforms, which changes how fees work in many cases. Ask any attorney you speak with to explain fees for your specific policy, in writing.
These rules apply to most current policies, but older losses and some policies follow different rules. That's one reason to have someone check the dates for your claim.
Steps to take before you call an attorney
You don't need everything organized to make the call, but these steps protect your claim:
- Report the damage promptly and write down your claim number.
- Photograph and video everything before cleanup or repairs.
- Prevent more damage with reasonable temporary repairs, like a tarp or water extraction. Most policies require it. Keep receipts and don't throw away damaged materials until they've been documented.
- Ask for everything in writing, including the adjuster's estimate, photos, any engineer's report and the denial letter.
- Don't sign a release or deposit a check marked "final" until you understand what it means.
- Request a certified copy of your policy so you have every page and endorsement.
Public adjuster vs. homeowners insurance attorney
| Public adjuster | Homeowners insurance attorney | |
|---|---|---|
| Documents and values the loss | Yes | Yes, often with outside consultants |
| Negotiates with the insurer | Yes | Yes |
| Interprets the policy as a legal contract | Limited | Yes |
| Handles appraisal | Sometimes | Yes |
| Represents you at an examination under oath | No | Yes |
| Sends pre-suit notice and files a lawsuit | No | Yes |
| How they're paid | A percentage of the claim, capped by Florida law | Explained in a written fee agreement |
A public adjuster can be a good fit for a straightforward valuation dispute. When a claim is denied outright, the insurer cites an exclusion or the deadline to sue is approaching, an attorney is usually the right call.
Frequently asked questions
Can I hire a homeowners insurance attorney after the insurer already paid something?
Usually, yes. Many homeowners call after receiving a partial payment that won't cover repairs. As long as you haven't signed a release that closes the claim, an attorney can review the payment, the estimate behind it and your policy, and help you file a supplemental claim if appropriate.
Will hiring an attorney make my insurance company cancel my policy?
Florida law limits when and how insurers can cancel or decline to renew policies, and they generally can't cancel simply because you made a valid claim or hired a lawyer. Insurers do look at claim history at renewal, though, so ask your attorney about your specific situation.
How much does a homeowners insurance attorney cost?
It depends on the case and your policy. Many property claim attorneys work on a contingency basis, which means no fee unless they recover for you. Because Florida changed property insurance fee rules in late 2022, ask for a written explanation of fees and costs before you sign anything.
Your home is likely your largest investment, and your policy is a promise to help protect it. If your insurer denied, underpaid or stalled your claim, get a free policy review. We'll read your policy with you, explain your options plainly, and push back when the facts support it. See the property claims we handle.
Written by
Simon Nicholson, founding attorney
Founded the firm after 15 years serving families in Guatemala and Mexico.
Read Simon’s bioThis article is general information about Florida law, not legal advice for your situation. Laws change, and every case is different. Reading it doesn’t create an attorney-client relationship.